
Plenty of companies say they do competitive intelligence. Far fewer can tell you who the competitor put on the call, how the renewal quote read, or where the demo quietly fell apart. That gap is the whole story of modern CI: the function is common, the headcount is thin, and most of what it reads is the same public material every rival is already reading.
Mystery Demo works on the part of that gap a desk cannot reach. Its team books competitors’ real sales demos as a buyer, asks the questions a buyer would ask, and hands back the recordings and an analysis of what each rep said, showed and quoted, all on one board.
One honest note on sourcing: the freshest, glossiest CI numbers tend to come from the CI software vendors themselves, which is a little like asking a barber whether you need a haircut. Every figure below comes from academic, practitioner and market research instead, even where that makes it a few years older, and each one is footnoted to where it was first published. If you only keep a handful of these, keep these:
Competitive Intelligence Has Become a Formal Function
The first finding is that, where companies do competitive intelligence at all, it is no longer a side project. Competitive intelligence used to be a rare, elite capability. Among the companies that practice it, it is close to standard equipment now.
| Survey | Who was asked | What it found |
|---|---|---|
| Sewdass and Calof, 2019 | 264 CI practitioners worldwide, 63% of them SCIP members | 87% had some form of formal CI structure1; 13% had no formal CI unit1 |
| Calof, 2017 | 79 Canadian members of SCIP | 84.8% had a manager with CI responsibilities2; 61% had a formal centralized CI unit2; 9% did CI informally2 |
| Yap and Md Zabid, 2011 | 123 companies listed on Bursa Malaysia | 62% had a formal CI unit3; 62% practiced CI continuously3 |
The surveys asked different people, so their numbers are not one trend. The 2019 survey was built on the questionnaire of a 2006 global study, though. On that questionnaire, the share of practitioners with a manager responsible for CI rose from 50.2% in the 2006 study to 71.2% in 2019.1

The reason competitive intelligence feels less like a moat than it used to is hiding in plain sight. When a formal structure is the norm among the organizations that practice CI, having one is table stakes rather than an edge.
The edge has moved to what the function really does, and that is where the numbers get less flattering.
But the CI Team Is Usually Tiny
These numbers explain why fresh competitive material reaches an enablement team slowly: the people producing it are few and stretched. For a function this widespread, competitive intelligence is staffed like an afterthought. The typical CI “team” is one to four people, and for many of them CI is a part-time job.
| Survey | Who was asked | What it found about headcount |
|---|---|---|
| CI Foundation, 2006 | 500+ CI practitioners, surveyed in 2005 | almost half had one or fewer full-time-equivalent people supporting CI4 |
| Yap and Md Zabid, 2011 | 123 companies listed on Bursa Malaysia | of those with a formal unit, 83% had fewer than 10 full-time CI staff3 and 53% had two to five3 |
| Calof, 2017 | 79 Canadian members of SCIP | 38% had one full-time CI resource2 and 41% had two to four2 |
| Sewdass and Calof, 2019 | 264 CI practitioners worldwide | 33% had one or fewer full-time people supporting CI1 and 37% had two to four1 |
Where the function sits says the same thing. Among the Malaysian companies with a formal unit, 79% of CI units sat in marketing, market research or corporate planning.3 In the 2005 practitioner survey, about a third of CI functions ran as a stand-alone unit, up from 10% in earlier research.4
Put the size and the placement together and you get the real constraint. A one-person CI function buried inside the marketing team keeps a battlecard roughly current. Shopping a competitor end to end, taking its demo as a buyer, and pressing on its price takes hours that function was never staffed for.
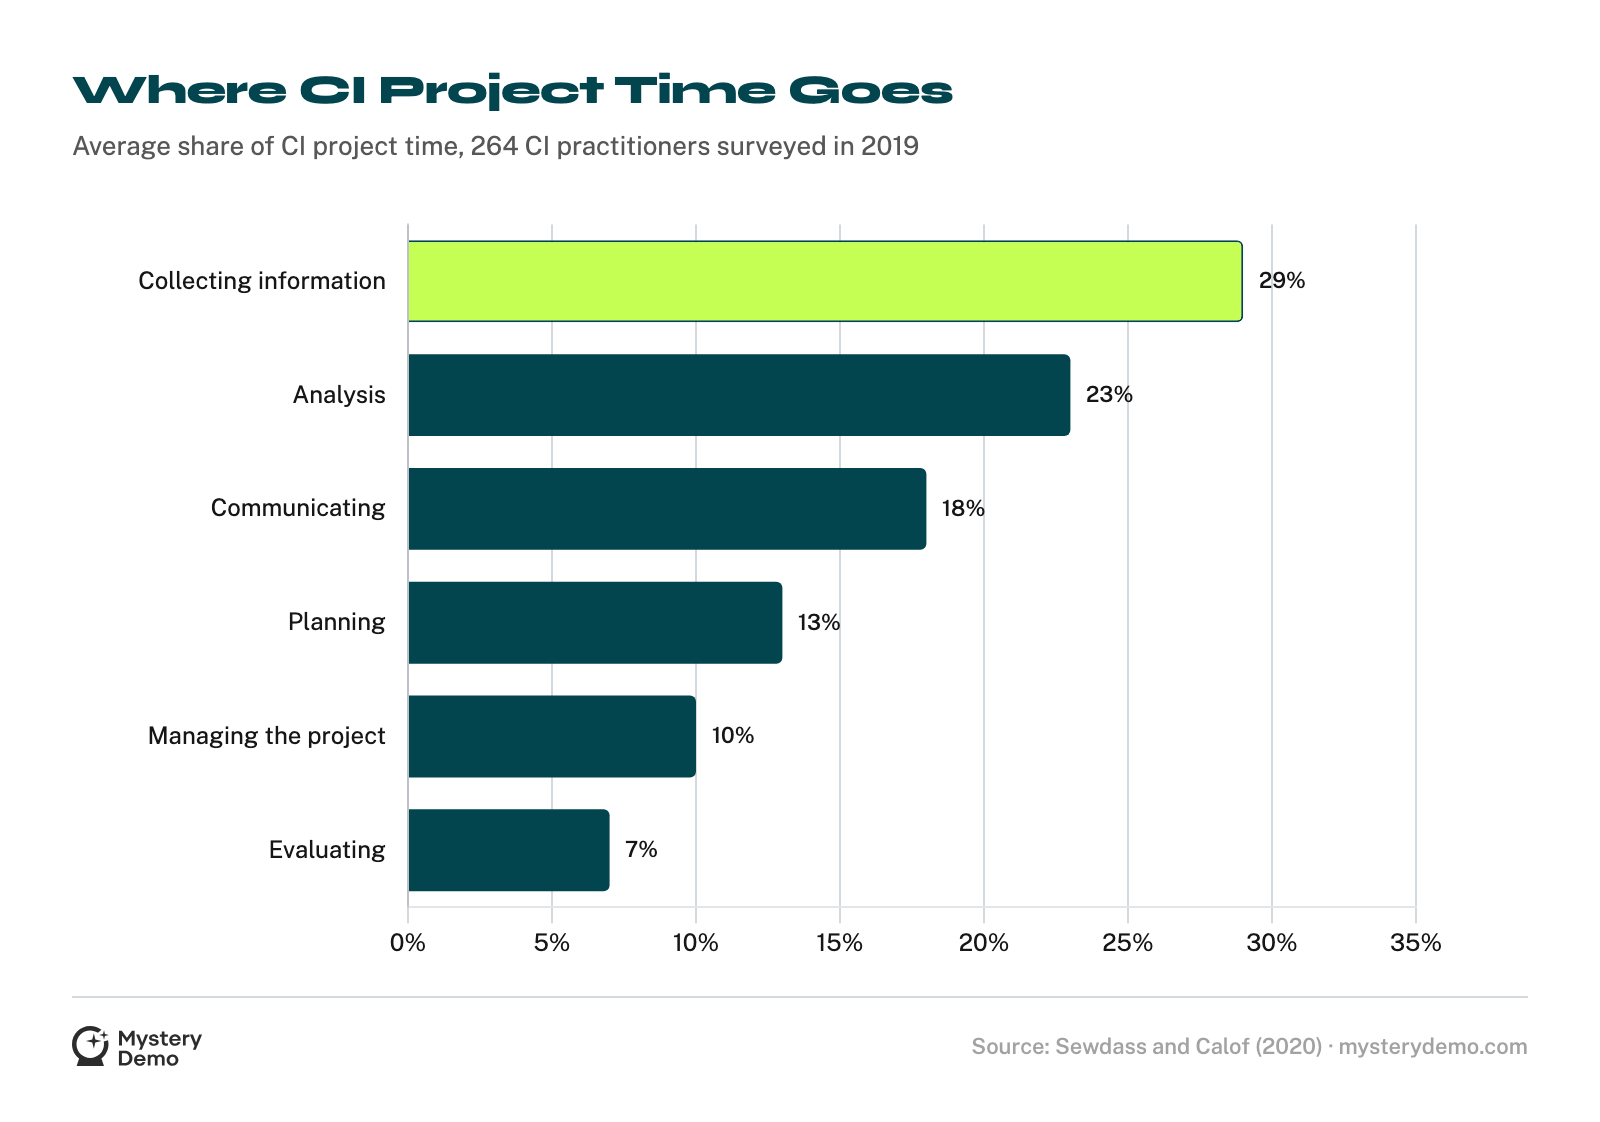
The constraint here is arithmetic. In the 2019 survey, collecting information took 29% of project time on average.1 When the whole function is one person or less, that share of the week leaves little room for booking a rival’s demos, so the work that survives is whatever can be done from a desk, and that quietly decides what counts as intelligence in most companies.
Most CI Is Desk Research, Not Field Work
This is why so much of the competitive material reps carry sounds alike: the dominant form of competitive intelligence is reading, and most of what gets read is the same public material every rival already has.
When the 2019 survey asked practitioners which sources matter most, desk sources took the top three places in its source table.1 Desk sources are read second-hand; people are asked first-hand, which is what researchers call primary research.
| Source | Kind | Rated very important |
|---|---|---|
| Free websites | desk | 52%1 |
| Publications, print or online | desk | 39%1 |
| Commercial databases | desk | 38%1 |
| Customers | people | 30%1 |
| Company employees | people | 29%1 |
| Industry experts | people | 28%1 |
This pattern should bother most heads of product marketing. If the most-used inputs are newspapers, the open web, and your own colleagues, then much of your competitive intelligence comes from sources your competitor controls or your team already believes.
No source on those lists is the rival’s own sales call, heard from the buyer’s side. The result is intelligence that is accurate about the public story and blind to the private one: the actual pitch, the actual objection-handling, the actual price after negotiation.
Desk research tells you what a competitor says. It cannot tell you what they do when a prospect is on the line.
Less Than Half of Practitioners See CI Used in Strategy
The test that matters to an enablement team is whether competitive intelligence changes a decision. By their own account, under half of practitioners see it used in strategic ones.
Our read: intelligence that changes a decision tends to be the kind nobody else has, gathered by watching how a competitor really sells rather than reading the press release everyone already has.
CI Spending Is Climbing
Spending on CI tools is set to keep growing, and the work is spreading to more teams.
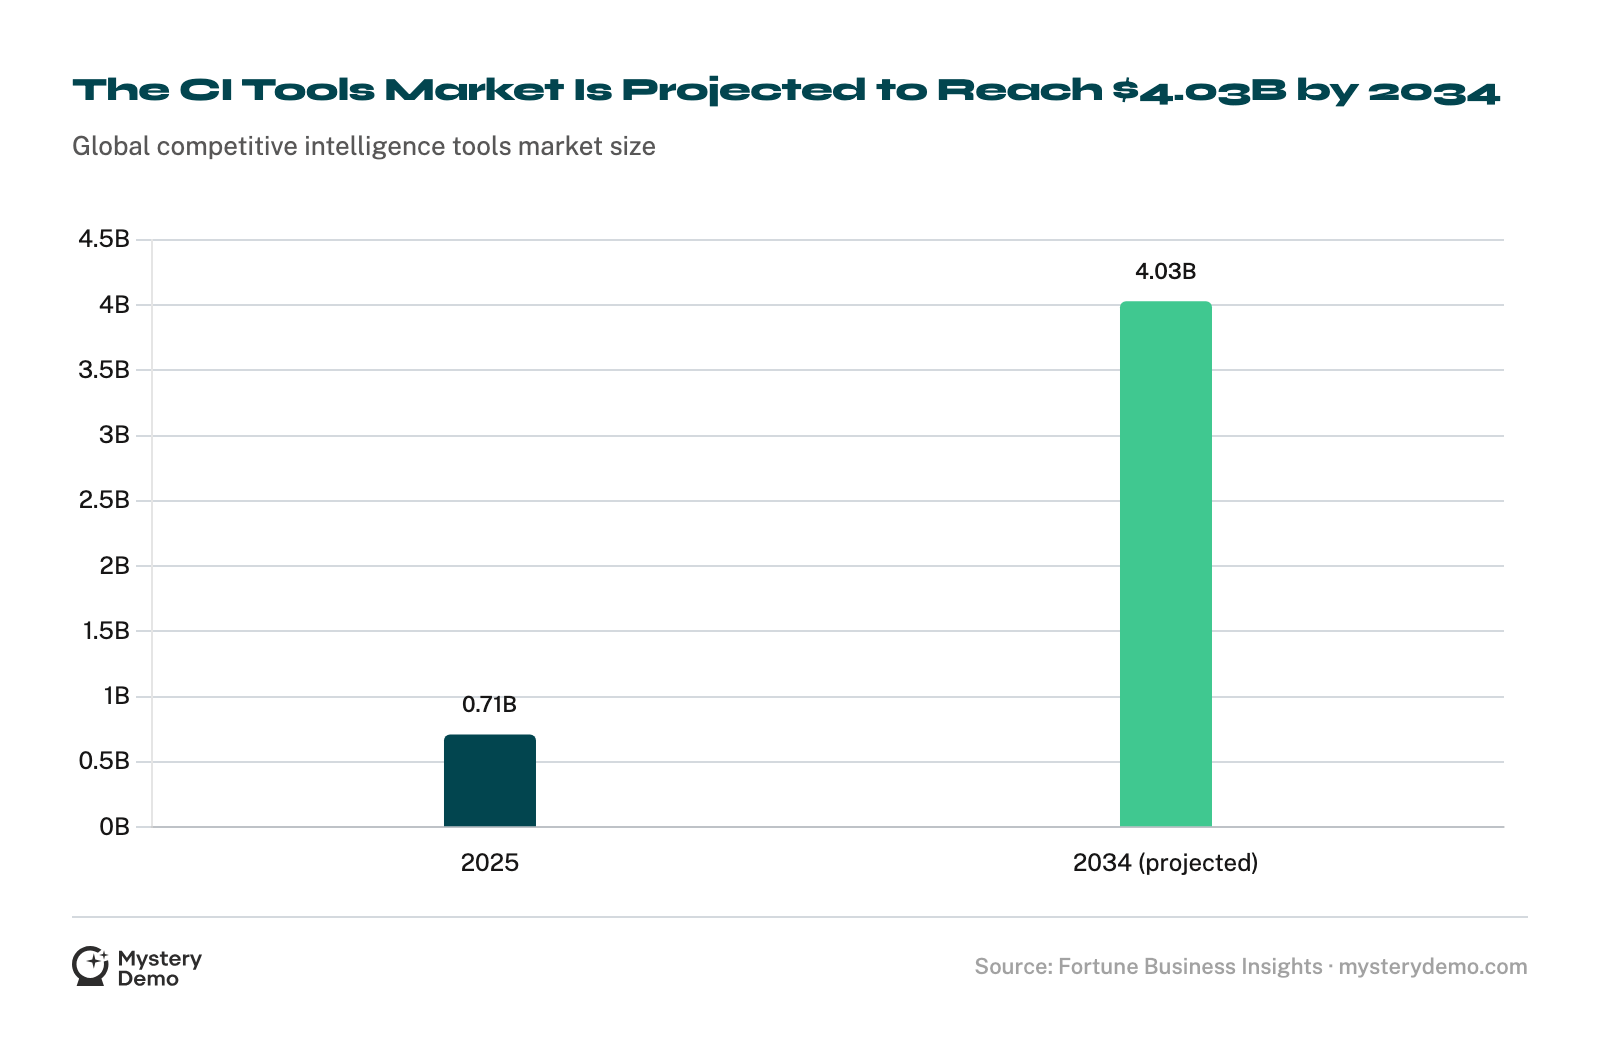
The spend and the spread point the same direction: competitive intelligence is being taken more seriously and pushed into more hands at once. That is both good news and a quiet trap, because more tools and more people scale a sourcing problem instead of fixing it.
A bigger budget aimed at the same public inputs just buys more of what your competitors already publish about themselves.
The investment only turns into an edge when some of it buys the buyer-side view a desk cannot reach: the real demo, the real pricing, the follow-up.
What Public Sources Cannot Tell You
Competitive intelligence built only from public sources is the intelligence your competitor approved for release. If your CI program is strong on the public record and thin on the private one, the cause is the one the whole industry shares: too little headcount and too few hours.

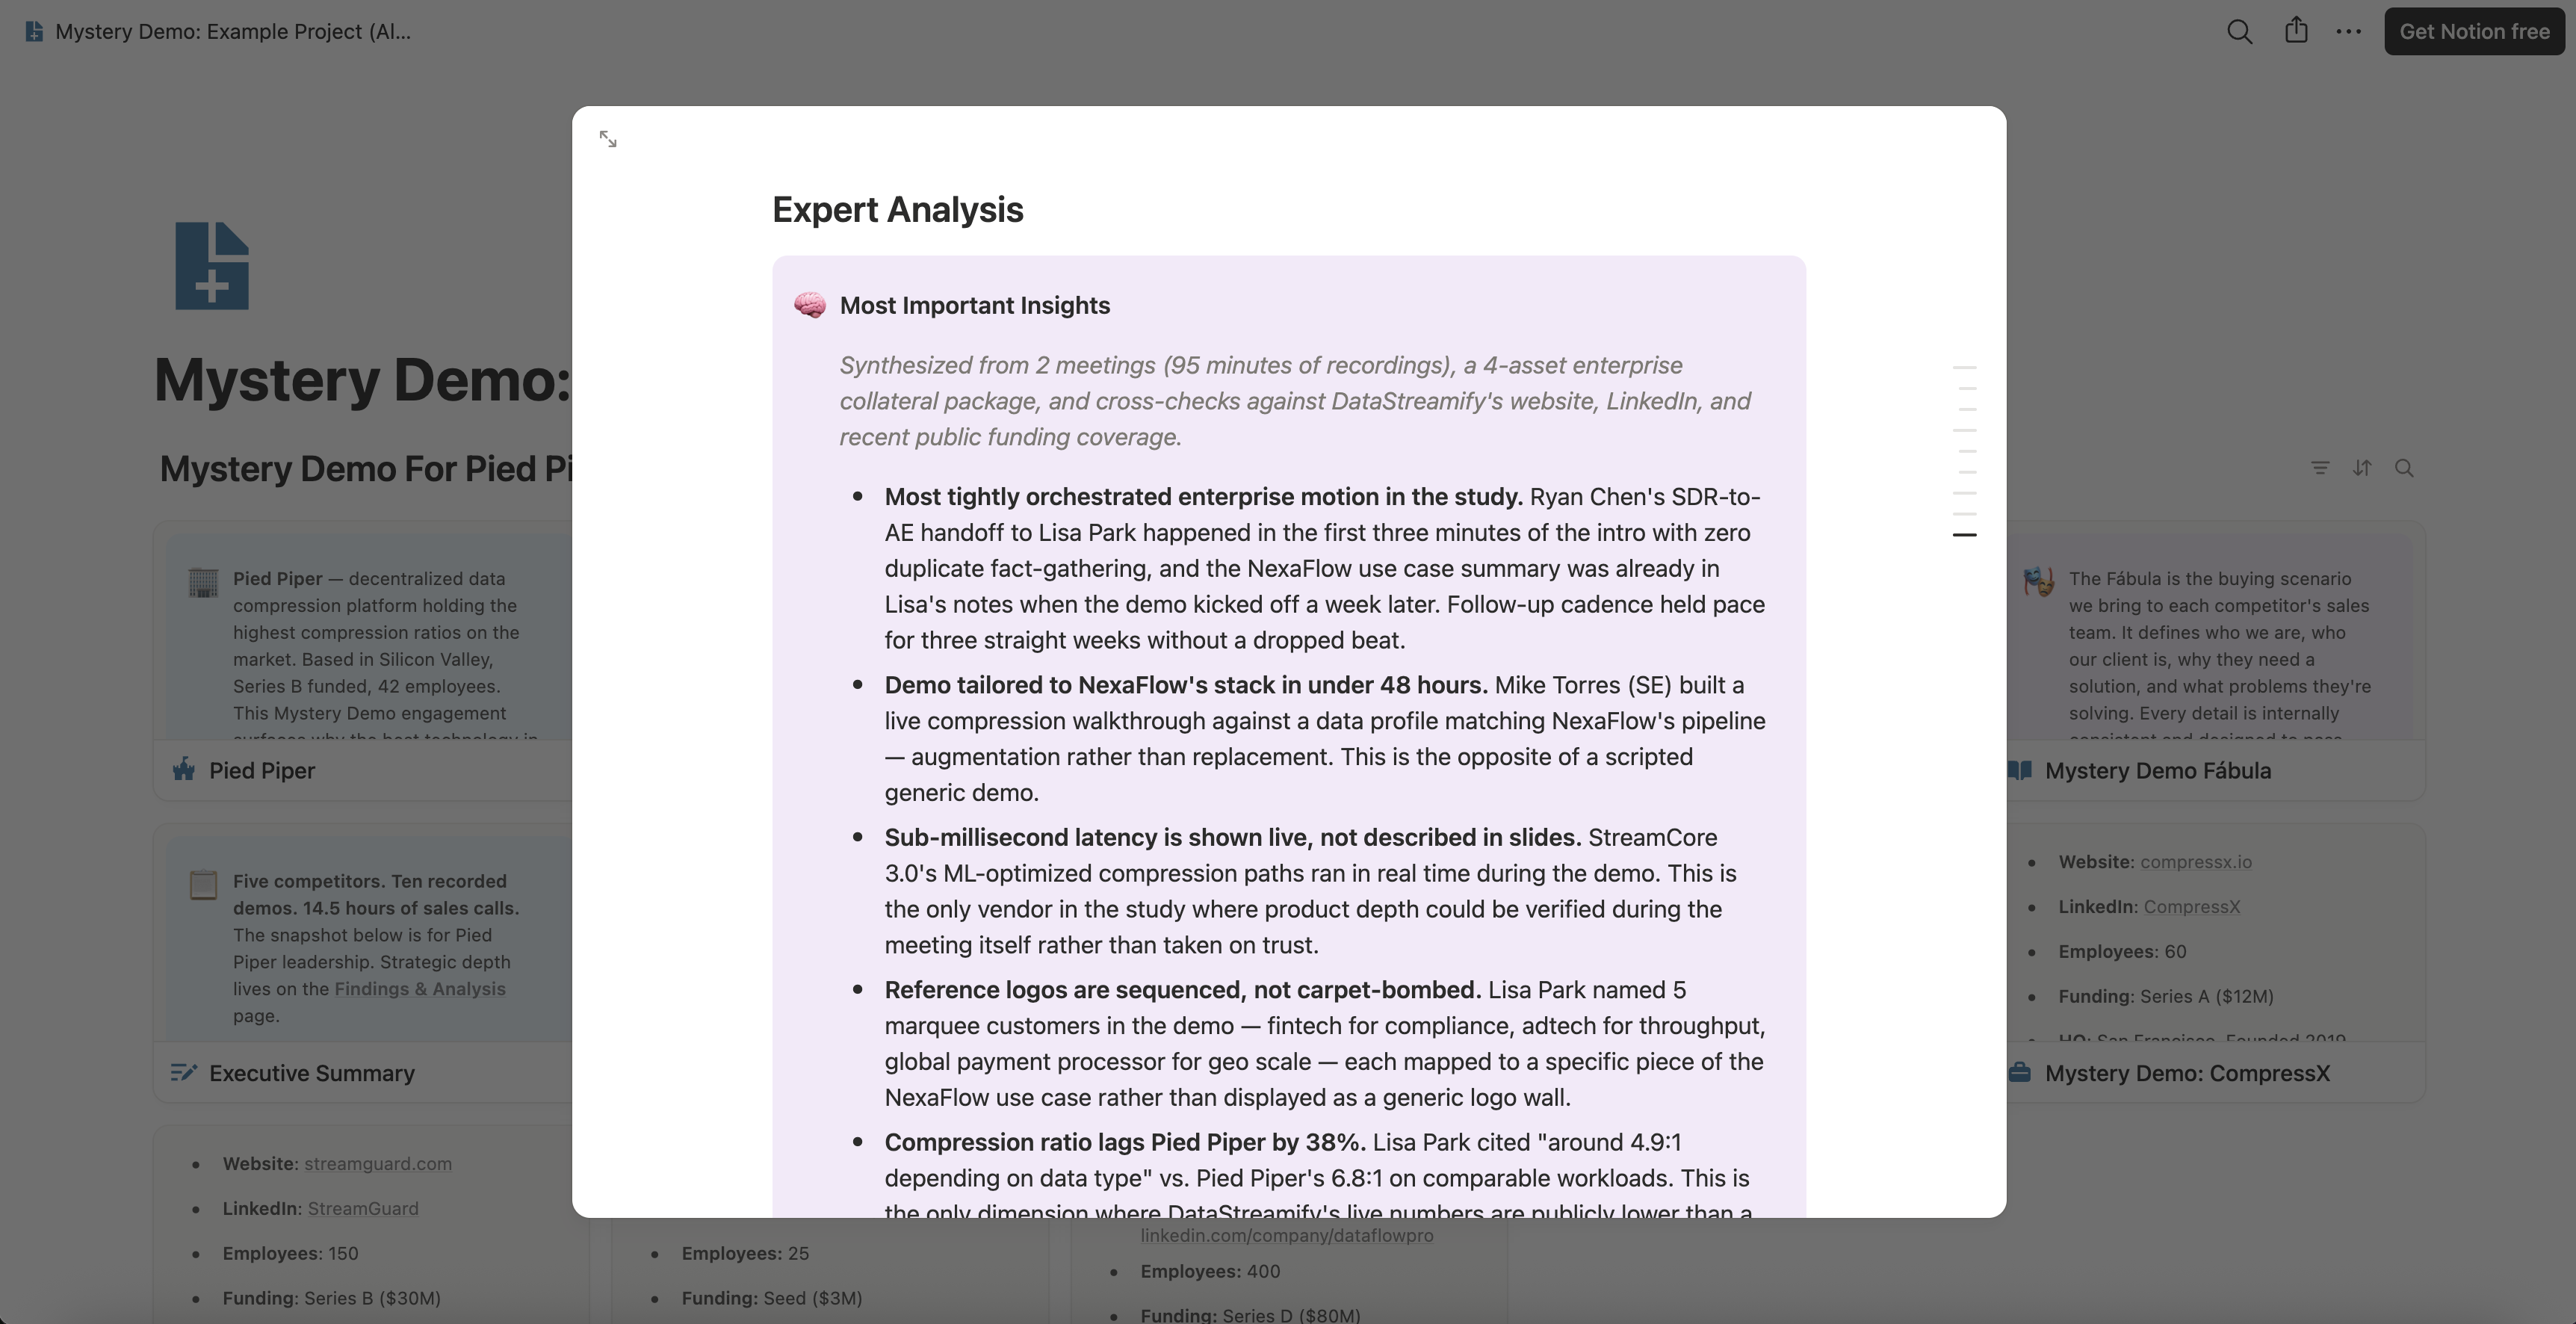
That is the Expert Analysis on one competitor’s page of our public example board, where the client and every competitor are invented. On a real board, every insight comes from the recorded calls (how a rival pitches, where it dodges, what it charges, and when it discounts), with each rep’s claims checked against the rival’s public record. Those pages feed the battlecard lines your reps carry and a competitor product comparison that sets every rival side by side.
Bring us your competitor list and your analysts can keep covering the public record while we go get the private one.
Frequently Asked Questions
What share of companies have a formal competitive intelligence function?
87% of organizations in a 2019 survey of 264 CI practitioners had some form of formal CI structure.1 In a broader sample of 123 companies listed in Malaysia, 62% had a formal CI unit in 2011.3
How big is a typical competitive intelligence team?
33% of practitioners had one or fewer full-time people supporting CI in the 2019 survey, and 37% had two to four.1 Among Canadian SCIP members in 2017, 38% had one full-time CI resource.2
Where does competitive intelligence sit in the org?
79% of CI units sat in marketing, market research or corporate planning among the Malaysian companies with a formal unit.3 In the 2005 practitioner survey, about a third of CI functions ran as a stand-alone unit.4
Do CI teams rely on primary or secondary research?
52% of practitioners rated free websites very important in the 2019 survey, the top source in its source table, with publications and commercial databases next.1 In 2005, practitioners rated secondary sources above primary ones.4
Do CI teams spend most of their time collecting information?
29% of project time went to collecting information on average in 2019, so most of the hours go to planning, analysis, communicating and managing the work.1
How often does competitive intelligence influence strategy?
42% of respondents to the Academy of Competitive Intelligence’s 2019 survey saw their CI used in strategic decisions, and 24% said their input was deemed critical.5
How big is the competitive intelligence tools market?
$0.71 billion in 2025, by one market-research firm’s estimate, which projects $4.03 billion by 2034.6
Is competitive intelligence a dedicated job or a shared skill?
30% of respondents were dedicated CI producers in the Academy’s 2019 survey, while 58% had been full-time producers in its 2015 survey; the other 70% in 2019 both produced and used intelligence.5
What is the biggest gap in most competitive intelligence programs?
33% of practitioners had one or fewer full-time people on CI in 2019, and their top-rated sources were desk sources.1 With that staffing, few programs have the hours to take a rival’s sales calls as a buyer.
References
- Sewdass and Calof: Contemporary Practices of Intelligence Support for Competitiveness, Foresight and STI Governance (2020)
- Jonathan Calof: Canadian Competitive Intelligence Practices, Foresight, Emerald Publishing (2017)
- Yap and Md Zabid: Acquisition and Strategic Use of Competitive Intelligence, Malaysian Journal of Library and Information Science (2011)
- Competitive Intelligence Foundation and Cipher Systems: State of the Art, Competitive Intelligence (2006)
- Academy of Competitive Intelligence: 2019 State of CI Impact Analysis (2019)
- Fortune Business Insights: Competitive Intelligence Tools Market, 2026 to 2034 (2026)
- Product Marketing Alliance: State of Product Marketing Report 2025 (2025)


